5G SA Adoption is Surging in the UK — What This Means for Consumers

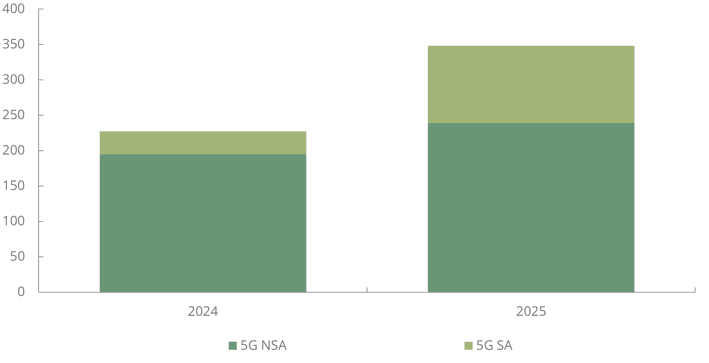
In November 2025, Ofcom released its Connected Nations UK Report; highlighting that 5G Standalone (SA) now accounts for approximately 31% of total 5G traffic in the UK. This means that 5G SA accounts for around 9% of cellular traffic now in UK, or 109PB of traffic. The growth in 5G SA traffic was part of a broader growth in 5G traffic, which grew by 53% in the past year from 227 PB to 348 PB.
5G NSA and 5G SA Traffic in the UK, 2024 vs. 2025
 Source: Ofcom
What is 5G SA and NSA?
5G SA is the next stage of 5G development; operating independently from 4G infrastructure, unlike 5G non standalone (NSA). The two technologies can be defined as the following:
- 5G NSA – this technology relies on the existing Evolved Packet Core (EPC) of 4G Long Term Evolution (LTE) networks, with 5G Radio Access Network (RAN) and the NR (New Radio) interface being used alongside the EPC.
- 5G SA – this technology, as 5G NSA, relies on 5G RAN and NR, however instead of the 4G LTE EPC, it relies on a 5G core. This enables the technology to offer improvements to KPIs (Key Performance Indicators) such as latency.
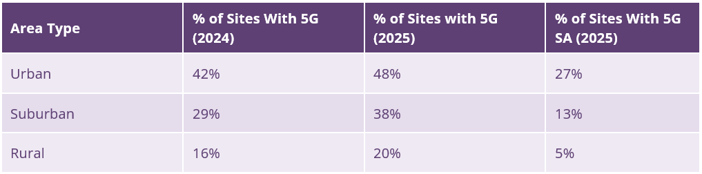
At present, the majority of 5G traffic in the UK relies on 5G NSA technology, with 69% of 5G traffic being delivered over 5G NSA. Juniper Research expects that both 5G NSA and SA will be critical to the UK mobile services market over the next five years, with 5G SA continuing to grow as a share of mobile network and 5G traffic. 5G NSA will remain important as it provides mobile network operators concentrating 5G SA expansion in high value locations such as urban areas. This can be seen in Ofcom’s reporting on 5G site deployment in the table below.
5G Site Statistics, 2024 and 2025
Source: Ofcom
Ofcom’s Update on 5G SA in the UK
Juniper Research believes that the growth in 5G SA traffic demonstrates how mobile network operators in the UK are beginning to accelerate their 5G SA strategies. According to Ofcom, 5G coverage in areas outside of premises where service is available from at least one MNO has reached 83% at a high confidence and 74% at a very high confidence. High confidence means at least an 80% probability of coverage, whilst very high confidence refers to around a 95% probability of coverage.
This is reflective of the expansion in 5G SA infrastructure, with mobile network operators having significantly expanding their deployments of 5G SA base stations. In the past year, the total number of 5G SA base stations grew from 3,300 to over 12,000, meaning 5G SA base stations now account for over 14% of total base stations in the UK.
Juniper Research expects that mobile network operators in the UK will continue to expand the coverage of 5G SA in 2026, with continued investment in upgrading or adding new base stations; positioning the UK market for further growth in 5G SA traffic. This will enable mobile network operators to deliver advanced connectivity to an increasing proportion of the population, and increasing the value of their existing 5G SA users through expanded coverage.
Is 5G SA Usage in the UK Primed for Growth?
Despite the growth in 5G SA traffic and capacity, Juniper Research believes traffic continues to lag behind the potential demand from mobile subscribers. Ofcom reports that 63% of 5G handsets is now 5G SA-capable in the UK, with 66% of mobile handsets being 5G capable. This means that whilst around 42% of mobile handsets in the UK is capable of supporting 5G SA, only 9% of the cellular traffic generated in the UK relies on 5G SA.
While part of this disparity is due to Fixed Wireless Access (FWA) deployments relying on 5G NSA, when accounting for this, Juniper Research believes that there is likely a strong disconnection between 5G SA capable mobile handsets, and actual usage. Consequently, Juniper Research believes that mobile subscribers will quickly be able to adopt the technology; laying the foundation for rapid growth.
However, mobile network operators will face considerable challenges when monetising the improved performance offered by 5G SA, with consumers in particular reluctant to increase mobile subscription costs.
To be successful in monetising 5G SA with consumers, Juniper Research believes that mobile network operators must not only pursue strategies oriented on the faster speeds and lower latency offered by the technology. 5G NSA and 4G are sufficient for most mobile services use cases, such as social media; diminishing the value of 5G SA.
Juniper Research believes that opportunities to monetise the additional capabilities of 5G SA amongst consumers will be more niche than in the enterprise market, however there will be opportunities. For example, there is potential for consumers to pay for additional uplink for major events they wish to broadcast video and audio from, as well as amongst mobile subscribers who work as influencers and frequently broadcast livestreams. Similarly, while gaming is unlikely to emerge as the market it was initially hyped to be, there will likely be niche demand from online gamers seeking to remain connected via mobile networks.
Overall, Juniper Research expects there to be considerable expansion in the 5G SA network capacity and availability, with traffic over 5G SA continuing to see strong growth over the next year. However, Juniper Research does not expect there to be a single killer use case for 5G SA amongst mobile subscribers, with cellular data growth unlikely to be driven by flashy use cases such as augmented reality. Instead, mobile network operators need to adopt diversified and more personalised strategies for their 5G SA monetisation; using technologies such as network slicing to deliver optimised services for subsections of mobile subscribers.
Alex is a Senior Research Analyst within Juniper Research’s Telecoms & Connectivity team, focusing on the latest developments in operator and telecommunications markets. His recent reports include Direct to Satellite, Network APIs, and Cellular IoT.
Related Research
-
 ReportMay 2025Telecoms & Connectivity
 Fred Savage
Operator Revenue Strategies Market, 2025-2029
Discover invaluable insights into trends and strategies for network operator revenue in our latest report, Network Operator Revenue Strategies. With data split across 60 countries, this extensive forecast analyses the dynamic and competitive network operator market and the current market challenges posed by slowing revenue, high market saturation in the consumer market, rising network ownership costs, and challenges in 5G monetisation.
VIEW -
 ReportMay 2026Telecoms & Connectivity
 Alex Webb
6G Market, 2026-2035
Our 6G Market research suite provides detailed analysis and strategic recommendations for mobile network operators developing their 6G roadmaps in the build up to its standardisation and launch.
VIEW
Latest research, whitepapers & press releases
-
 ReportNovember 2026Fintech & Payments
 Lorien Carter
Virtual Cards Market: 2026-2031
Our Virtual Cards research suite provides a comprehensive and in-depth analysis of the role of virtual cards in the digital payments landscape
VIEW -
 ReportNovember 2026Fintech & Payments
 Shane O'Sullivan
B2B Payments Market: 2026-2031
Our B2B Payments research suite provides a wide-ranging and rigorous analysis of this massive market; enabling stakeholders from B2B payment platform providers to regulators and banks, to understand future growth, key trends and the competitive environment.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Ardit Ballhysa
Robocalling & Branded Calling Market: 2026-2031
Our Robocalling & Branded Calling Market research suite provides insightful analysis of a market that is becoming increasingly dynamic and complex.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Peter Boyland
CPaaS Market: 2026-2031
Our CPaaS Market 2026-2031 research suite delivers insightful analysis of a market that will experience significant growth in the next five years. It provides an analysis of CPaaS vendors, key partnerships and client relationships, alongside intelligence on how to capitalise on changing market dynamics within the rapidly expanding CPaaS market.
VIEW -
 ReportOctober 2026Fintech & Payments
 Michael Greenwood
Accounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad Jahan
Crypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW


-
 WhitepaperNovember 2026Fintech & Payments
Lorien Carter
Is Agentic Commerce on the (Virtual) Cards?
Our complimentary whitepaper, Is Agentic Commerce on the (Virtual) Cards?, examines the state of the virtual cards market; explaining the role of key actors in the virtual cards landscape and recent developments within the virtual cards industry.
VIEW -
 WhitepaperNovember 2026Fintech & Payments
Shane O'Sullivan
The End of Wire Transfer – the Battle for B2B Payments
Our complimentary whitepaper, The End of Wire Transfer – the Battle for B2B Payments, examines the rapidly evolving state of the B2B payments market.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Ardit Ballhysa
Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond
Our complimentary whitepaper, Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond, explores the challenges and opportunities for fraud prevention.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Peter Boyland
Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS
Our complimentary whitepaper, Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS, explores the challenges and opportunities for operators and enterprises as CPaaS becomes more embedded in the consumer experience.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW


-
Telecoms & Connectivity
Private Networks in Service to Exceed 47,000 Globally by 2031, as Industry Specialisation & 5G Drive Expands
November 2026 -
Fintech & Payments
Virtual Cards Market Leaders Revealed by Juniper Research, as Revenue Forecast to Hit $148 Billion by 2031
November 2026 -
Fintech & Payments
B2B Payment Transactions to Exceed 612 Billion by 2031, as Fintechs Challenge Banks for Business Payment Relationships
November 2026 -
Fintech & Payments
27th NextGen Payments & RegTech Forum Returns to Limassol, Cyprus
November 2026 -
Telecoms & Connectivity
North American Consumer Losses from Fraudulent Robocalls to Fall by a Third by 2031; Driven by Robust Solutions and Branded Calling
November 2026 -
Telecoms & Connectivity
CPaaS Market Value to Exceed $50 Billion Globally by 2031, as Infobip, Twilio, and Sinch Identified as Market Leaders
November 2026