SoftBank’s High Altitude Strategy: The Growing Role of LEOs and HAPs in Global Connectivity

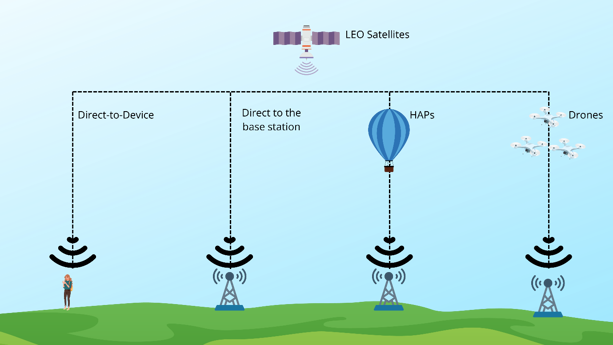
Japan-based network operator SoftBank has recently joined a consortium to develop and test space-based optical connectivity technologies to explore integrating non-terrestrial solutions, such as satellites and high-altitude platforms (HAPs), with ground-based stations. The consortium will launch low-earth-orbit (LEO) satellites in 2026 to test wireless optical communication technologies, followed by HAP launches in 2027. Softbank will develop the wireless communication equipment and integrate it with the HAPs systems. Kirohara Optics will build the optical communication terminals, and ArkEdge Space is responsible for the LEO satellites.
As we approach the 6G era, Juniper Research believes these architectures will become commonplace over the next 10 years; owing to their inclusion in telecoms standards, their ability to provide increased coverage at a lower cost, and the network redundancy they add to connectivity service providers.
The Role of LEOs and HAPs in Connectivity
Source: Juniper Research
A key differentiator here is the use of optical wireless technologies, rather than radio frequency radio frequency (RF) waves that are commonly used in telecoms networks today. However, while RF waves are well-suited to terrestrial networks today, several limitations may dissuade network operators from implementing them in satellite networks. These include:
- Risk of signal interception: RF signals can be more easily intercepted than optical wireless technologies, which require further investment into encryption of traffic whilst in transit. Additionally, any losses related to signal interception will diminish the value of a satellite-based network.
- Atmospheric interference: Given the large distances between network nodes and the high altitudes in networks, the changing atmospheric conditions can have substantial impacts on the consistency of network provision when RF waves are used. However, certain bands, such as the L band, are more resistant to changes in atmospheric conditions. Moreoverver, the correct placement of HAPs, including drones or balloons, can reduce the impact of interference across all bands.
- Power constraints: RF waves require heavy power consumption; requiring the equipment for antennas and amplifiers to be larger, which will result in challenges for LEO satellites and smaller HAPs.
- Spectrum congestion: There is already a heavily regulated process for spectrum allocation and acquisition in the satellite space. Additionally, as demand for satellite connectivity is expected to increase, Juniper Research predicts the cost of spectrum acquisition to rise.
Which Industries Will Drive Satellite Revenue Growth?
Juniper Research expects operators and satellite network operators (SNOs) to struggle in monetising satellite services directly. Primarily, most cellular connections are attributable to consumers (ie smartphones, tablets and other consumer devices), and the average consumer is unlikely to be willing to spend more with their network operators for specific coverage in rural or remote areas.
Operators must focus on growing revenue through enterprises, but these industries differ in their needs and requirements. Requirements such as high data throughput, fixed network end nodes, and low latency are ubiquitous across industries that will demand wireless optical technology. Juniper Research has identified the following sectors that will benefit from the technology’s introduction:
- Cloud Service Providers: Cloud providers require ultra-fast, secure data transmission between global datacentres to support real-time services and backups. Wireless optical satellite links offer high-capacity, low-latency communication without relying on congested undersea cables or RF spectrum. This enables more resilient and scalable infrastructure for cloud computing and edge services.
- Maritime: Ships and offshore platforms operate in remote regions where terrestrial and RF-based connectivity is limited or unreliable. Wireless optical satellite links provide high-speed, interference-free communication for navigation, logistics, and crew welfare. This improves operational efficiency and safety, while supporting digital transformation at sea.
- Smart Energy: Smart grids, wind farms, and solar installations often span vast or remote areas that lack robust terrestrial connectivity. Wireless optical technology enables secure, high-bandwidth data exchange between satellites and ground-based energy assets. This supports real-time monitoring, predictive maintenance, and efficient energy distribution.
- Military & Defence: Military operations demand secure, resilient communication across global theatres, often in contested or remote environments. Optical satellite links are harder to intercept or jam than RF; making them ideal for encrypted, mission-critical data transfer. They support battlefield awareness, drone coordination, and strategic command systems.
- Remote Infrastructure: Mining sites, research stations, and large-scale construction projects often operate far from traditional networks. Wireless optical satellite communication enables reliable, high-speed connectivity for automation, safety systems, and remote diagnostics. This reduces downtime, enhances productivity, and supports digital integration across isolated assets.
What Does Juniper Research Expect to Happen?
We believe there will be increased investment in wireless optical technologies. This technology uses modulated light to transmit data through the air and vacuums; providing high-speed, secure communication. Unlike RF technologies, it does not rely on radio waves or spectrum licensing; making it ideal for environments with RF congestion or restrictions. However, it must be noted that it requires line of sight, and the level of service is also dependent on weather conditions.
Given the differences between RF-based technologies and optical wireless networks, how do network operators implement these technologies to maximise revenue generation? Both technologies offer distinct benefits and constraints, therefore Juniper Research believes that future LEO-based networks will include both technologies, and Softbank must ensure it can test satellites with both antennas moving forward.
However, while increased coverage has been outlined as a key benefit of using satellites, it must be stressed that this creates issues with indoor coverage. The idea that satellites will ‘commoditise’ wireless connectivity is not proper. Other technologies must be used in conjunction with satellites for actual ubiquitous coverage. Indeed, as we approach the 6G era, we expect network operators to use a range of different network equipment types, such as HAPs and other small cells, to maximise indoor and outdoor coverage. The challenge operators face is minimising the investment needed to provide maximum coverage.
As VP of Telecoms Market Research at Juniper Research, Sam produces high-quality research on telecommunications technologies and the future of digital content. His recent reports include 5G Satellite Networks, CPaaS, and Operator Revenue Strategies. Sam has been interviewed by leading media outlets, including the BBC and Wall Street Journal, and is a regular contributor to messaging conferences and telecommunications industry events.
Related Research
-
 ReportJuly 2026Emerging Technology
 Saffron Dusanjh
VLEO Satellite Market, 2026-2031
Our Very Low Earth Orbit (VLEO) Satellite Market research suite provides comprehensive analysis of one of the fastest-emerging markets within the global space economy.
VIEW -
 ReportMay 2025Telecoms & Connectivity
 Fred Savage
Operator Revenue Strategies Market, 2025-2029
Discover invaluable insights into trends and strategies for network operator revenue in our latest report, Network Operator Revenue Strategies. With data split across 60 countries, this extensive forecast analyses the dynamic and competitive network operator market and the current market challenges posed by slowing revenue, high market saturation in the consumer market, rising network ownership costs, and challenges in 5G monetisation.
VIEW
Latest research, whitepapers & press releases
-
 ReportNovember 2026Fintech & Payments
 Lorien Carter
Virtual Cards Market: 2026-2031
Our Virtual Cards research suite provides a comprehensive and in-depth analysis of the role of virtual cards in the digital payments landscape
VIEW -
 ReportNovember 2026Fintech & Payments
 Shane O'Sullivan
B2B Payments Market: 2026-2031
Our B2B Payments research suite provides a wide-ranging and rigorous analysis of this massive market; enabling stakeholders from B2B payment platform providers to regulators and banks, to understand future growth, key trends and the competitive environment.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Ardit Ballhysa
Robocalling & Branded Calling Market: 2026-2031
Our Robocalling & Branded Calling Market research suite provides insightful analysis of a market that is becoming increasingly dynamic and complex.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Peter Boyland
CPaaS Market: 2026-2031
Our CPaaS Market 2026-2031 research suite delivers insightful analysis of a market that will experience significant growth in the next five years. It provides an analysis of CPaaS vendors, key partnerships and client relationships, alongside intelligence on how to capitalise on changing market dynamics within the rapidly expanding CPaaS market.
VIEW -
 ReportOctober 2026Fintech & Payments
 Michael Greenwood
Accounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad Jahan
Crypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW


-
 WhitepaperNovember 2026Fintech & Payments
Lorien Carter
Is Agentic Commerce on the (Virtual) Cards?
Our complimentary whitepaper, Is Agentic Commerce on the (Virtual) Cards?, examines the state of the virtual cards market; explaining the role of key actors in the virtual cards landscape and recent developments within the virtual cards industry.
VIEW -
 WhitepaperNovember 2026Fintech & Payments
Shane O'Sullivan
The End of Wire Transfer – the Battle for B2B Payments
Our complimentary whitepaper, The End of Wire Transfer – the Battle for B2B Payments, examines the rapidly evolving state of the B2B payments market.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Ardit Ballhysa
Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond
Our complimentary whitepaper, Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond, explores the challenges and opportunities for fraud prevention.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Peter Boyland
Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS
Our complimentary whitepaper, Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS, explores the challenges and opportunities for operators and enterprises as CPaaS becomes more embedded in the consumer experience.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW


-
Telecoms & Connectivity
Private Networks in Service to Exceed 47,000 Globally by 2031, as Industry Specialisation & 5G Drive Expands
November 2026 -
Fintech & Payments
Virtual Cards Market Leaders Revealed by Juniper Research, as Revenue Forecast to Hit $148 Billion by 2031
November 2026 -
Fintech & Payments
B2B Payment Transactions to Exceed 612 Billion by 2031, as Fintechs Challenge Banks for Business Payment Relationships
November 2026 -
Fintech & Payments
27th NextGen Payments & RegTech Forum Returns to Limassol, Cyprus
November 2026 -
Telecoms & Connectivity
North American Consumer Losses from Fraudulent Robocalls to Fall by a Third by 2031; Driven by Robust Solutions and Branded Calling
November 2026 -
Telecoms & Connectivity
CPaaS Market Value to Exceed $50 Billion Globally by 2031, as Infobip, Twilio, and Sinch Identified as Market Leaders
November 2026