Tackling the New Fraud Landscape: An Interview with Mastercard

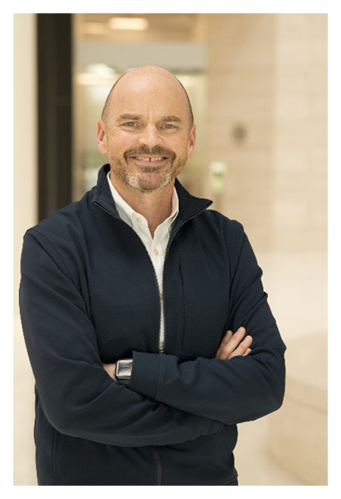
Our VP of Fintech Market Research, Nick Maynard, recently caught up with Chris Reid, Executive Vice President, Identity Solutions at Mastercard, about Mastercard’s view of the market and what steps it is taking to address fraud and scam risks.
Chris Reid is Executive Vice President for Identity Solutions globally at Mastercard. In this role, he is responsible for the division containing Identity Services such as Identity Verification, Payment Authentication, biometric solutions and the development of Mastercard’s Digital Identity including Device and dynamic Personal Identity capabilities.
Mr. Reid joined Mastercard in April, 2008 and has managed the company’s global relationships with some of the world’s leading Financial Institutions as well as more recently, leading the North America Services group containing Cybersecurity and Intelligence Solutions, Consulting, Data and Analytics and Loyalty Solutions.
Prior to joining Mastercard, Mr. Reid spent ten years at Tesco, one of the world’s largest retailers in a variety of Operational and Marketing roles including Tesco.com. Mr. Reid then spent time at Barclays Bank where he headed up the Customer Strategy and Planning team and then took accountability for all of the customer communications for the Retail Bank. Mr. Reid was born and raised in Scotland and holds a bachelor’s degree in Hospitality Management.
NM: What changes is Mastercard seeing in the way scammers are trying to exploit victims?
CR: Unfortunately what we are seeing is a huge surge in scams, and that really is a global phenomenon. In the US, according to the FBI in 2023, we saw a 22% year on year growth in consumer scam losses. In the UK, fraudsters were responsible for nearly 1.4 million thefts during the first half of 2023, that’s the equivalent of one every 12 seconds. What we are seeing within those scams is purchase scams, thinking you are buying something and you’re not, in the UK that’s now more than half of scams, investment scams are amongst the most costly, according to the FTC over here, as in the UK.
As more people are embracing real time payments, the account to account payment scams are really growing rapidly, referred to as authorized push payment fraud. Again in the UK, that accounts for 40% of all UK brand fraud losses. Those statistics are truly awful, which is why have a passion. But we also know that those are just the crimes that are reported, where this is somewhat unique is the impact of the victim is much greater than traditional payment fraud. By the nature of its name, the victim has actually sent money to the fraudster, the victim was very active in this crime, and so what we know is, many victims are either too ashamed or just afraid to come forward, and so that growing threat of scams that we’ve seen, the growing awareness and fear of them, it is really putting our financial institution customers under real pressure.
77% of consumers worldwide believe that their banks should be offering a better protection against scams, and so the stakes for businesses and consumers alike couldn’t be higher now, that’s why we are taking a multipronged approach to fighting scams, and that’s really the changes and momentum we’ve seen in the wrong direction over the last 12 to 18 months.
NM: This is scary and we are seeing major significant shifts. One of the biggest developments right now is AI, and what role it has. What role do you see AI being, both in preventing fraud and at the hands of scammers?
CR: You described it just there, the statistics and momentum is really scary, we should all be worried. If we can’t have faith in the digital economy, it is not going to be an enabler of growth and commerce of all shapes and sizes. Really what is driving that is the scammers embracing sophisticated technologies like AI to deceive their victims. Scams these days are incredibly convincing, and so that leaves us all more vulnerable, whether we are victims or not.
On the other hand, we know that AI can be used for good, in fact at Mastercard, we’ve been using AI for the better part of the last decade, and it’s now a foundational technology used across our business. It’s been a game changer in helping to identify patterns in fraud, it allows us to move way beyond the rules based decisioning framework of if this then that, where you get to with an AI driven solution and model is you get a much greater degree of accuracy, you get a much more timely result. Thinking again about the scams, for decades the crime we had to worry about in payment fraud was really somebody who isn’t you pretending to be someone else, whether that was a piece of plastic that was lost, stolen or counterfeit, and the same online, and now what we’re looking for is that it is you, we are looking to detect anomalies in behaviour and payments.
AI, as I mentioned, is really foundational technology for us. In the last year alone, our AI powered security solutions have stopped over £20 billion in fraud losses, and it really is the advancement of those that we have launched into our suite of specialized solutions, particularly to identify and prevent scams.
NM: How is Mastercard meeting the challenges within fraud prevention, and what is Mastercard’s key approach to this challenge?
CR: It's really around digging into the tech. Our AI-based solutions range from biometric and identity solutions, to real time transaction decisioning scores, and when we combine those, we believe we are truly offering a compelling anti scam protection layer to both financial institutions, our bank customers, and their consumers.
If we start with the beginning of a digital journey, it starts with the beginning of a relationship, that account opening. Scammers open or take over new accounts to fraudulently apply for credit, create these so called mule bank accounts or drop bank accounts, and that’s to receive stolen funds, or to impersonate someone using a false or synthetic identity. So what our identity capabilities are doing is they are verifying someone is who they say they are, throughout the lifecycle of that account, the account opening, we are stopping scammers opening accounts with that false or collage of synthetic identity data, or stopping someone taking over someone’s account.
The second layer is the account to account or card based payment, but in this case, it’s really account to account is initiated. Our behavioural biometrics understand how a consumer is using a device, it could be a mobile phone, laptop or desktop, what we are looking to assess is those physical interactions across the devices, to identify any unusual behaviour. That could be because you are being coached and there are pauses and the scammer is coaching you, or being terrible and nefarious and coercing you, you are just not as confident as you normally are when making a transaction. We’re looking for a set of signals we know we have to be looking for, that is getting into a micro layer of insight into there might be something going on with your behaviour, due to the way you are interacting with the website or the app
For account to account payments, we have a really good solution, it’s called Consumer Fraud Risk, this provides the banks with intelligence to detect and prevent scams in real time. This solution is now live in the UK with ten large banks, it uses AI and our unique views on scams and mule behaviour, and as I mentioned real time is so incredibly important, because the money is being sent in real time, so what we are doing is we’re giving banks the opportunity to intervene, to stop a payment to a criminal, before the funds are sent, and to engage their consumers in a dialogue. When a consumer is initiating an account to account payment from a bank account, our open banking solutions are also confirming the account ownership and validating the identity details of where it’s going to. So, I’ve just run through a variety of solutions, that is deliberate.
Unfortunately there is no single silver bullet to detecting and stopping scams, it’s a multilayered approach of insight at various points of the customer journey, and then the connection between all of that and bringing it together, ultimately its to stop the consumer doing something they want to do, and that’s why its so difficult.
NM: We hear a lot from lots of different fraud prevention vendors, it’s a pretty competitive market in terms of our solutions can prevent 99% of fraud, or they have this success rate. In that context of so much competition, what makes Mastercard unique, what is that killer capability?
CR: Your context for that is completely accurate, there is just a proliferation of statistics and data being communicated, and so, I focused on the technology and our AI capabilities before, I always argue technology without world class implementation is a bit like a one handed clap, it could have been great but it wasn’t. We know partnerships across the ecosystem are critical in fighting scams and protecting consumers. I do not believe any single entity is going to provide the solution alone – we mentioned before how scams are becoming more complex, it’s a growing problem. We have to collaborate with other organisations to tackle them in my view.
That’s why we have teamed up with NatWest, a very large financial institution in the UK, Verizon one of the largest leading telco companies in the US, and the Global Scam Alliance to fight these scams.
With NatWest, we’re looking with ten large banks, NatWest is one, we’re using large scale payment data to identify those scams before the funds leave the victims account. We’ve been working with banks really for the last several years also, looking at scam funds and where they move through the financial ecosystem, through these so called mule accounts, to disguise them and to get them out of the system. We’ve been working with all of the banks, because the fraudsters will move their funds across the institutions, what we’ve been able to do is help provide the connection point and the linkages, and so based on those insights from the tracing activity and overlaying them with specific analysis, we get to understand the accounts associated with scams, and that get its there
So Verizon, a fraudster has to communicate with the victim, often via the phone. We are building on what has been a very valued and long standing partnership with Verizon here in the US to fight these scams. Specifically, we are building new solutions to more accurately block scammers and detect them, using our identity insights combined with the technologies we have as well as Verizon’s capabilities. We all receive phones calls and texts every day that we don’t recognise, and many of those are going to be coming from scammers, trying to build a relationship and coercing us into sending accounts. So, with Verizon, we want to stop scammers from initiating that contact in the first place. Outside of the US, we’re in discussions with other telcos in terms of collaborating on new solutions there. We’ve developed partnerships with what we call the channel partners, this is around how does financial institution get access to these solutions as simply as possible.
So, we’ve got a really good partnership with Entersekt, they are a global financial authentication company, uses our Mastercard Identity solutions to help financial institutions who will use the Entersekt stack, using the behavioural biometrics, banks can step up high risk transactions, they can verify the sender, they can also potentially send a message to the receiving bank, and that extra step is protecting senders before the funds leave the account. Finally, those three around things that for a consumer are behind the curtain. We are also partnered with the Global Anti Scams Alliance, really what we are partnering with them to do is to just drive consumer awareness campaigns, to educate consumers, I go back to its becoming incredibly sophisticated, and it is, so as well as what goes on behind the scenes to help consumers, there really is the opportunity to educate all of us. For those of us who have the privilege and are a bit more aware and knowledgeable, whether it’s a parent, a spouse, a family member, a son or a daughter, or just a friend, they don’t have that element of knowledge, so the consumer awareness campaigns with the Global Anti Scam Alliance are going to be really important for us.
NM: What do you see the future of online fraud as? We’ve seen so many changes from card present to card not present, to account takeover fraud, to APP with real time payment systems, where are we headed next?
CR: I do think there are several trends that we have spoken about a bit, that are likely to shape the landscape going forward. As technology advances, and AI will be a big part of this, but as other technology advances, so too will the techniques of fraudsters and the capabilities of fraudsters. The bad actors, the criminals are going to continue to evolve, every single day, in every financial institution, there are tens of thousands of people around the world doing everything they can to understand how fraudsters are behaving and stop it, they are targeting those emerging technologies.
I think identity theft and social engineering attacks are going to become more sophisticated, but our tools to prevent and detect them are becoming more sophisticated. One of things we are going to see potentially is that the value of a crime may actually increase, because if you think about it, fraud is a business, it’s a significant business, fraudsters are looking for and will have will have a targeted return on investment in the same way that legitimate businesses have. If a fraudster is using more advanced technology, that’s likely going to be more expensive for them, so I think what we’re going to see, particularly in APP fraud, the value of the loss and specific likely getting higher, as it costs criminals more to be successful.
That’s terrible, because you begin to get into real financial ruin for consumers, that’s why, again, I think I said this at the beginning, that’s why we have a passion for this. We are, and we will continue to invest in these advanced anti-fraud and anti-scam solutions, because the direction of travel will become more dangerous for society, there will be more adverse impacts for consumers, and so if we are investing more, if we’re driving consumer education and awareness, and that’s critically important as I mentioned, we are going to empowering organisations and individuals in the digital economy to be vigilant, to be able to recognise, mitigate and report online crime.
Unfortunately, my summary is, I think it's going to continue to be a competition between bad actors and good actors, and I know from speaking to our valuable customers, we are all committed to win this competition, we’re going to do whatever it takes.
To find out more about Mastercard’s Identity portfolio, please visit: https://b2b.mastercard.com/account-identity-services/
Click HERE to learn more about the Future Digital Awards, including the Fintech & Payments Awards 2024 - closing 16th August!
Latest research, whitepapers & press releases
-
 ReportNovember 2026Fintech & Payments
 Lorien Carter
Virtual Cards Market: 2026-2031
Our Virtual Cards research suite provides a comprehensive and in-depth analysis of the role of virtual cards in the digital payments landscape
VIEW -
 ReportNovember 2026Fintech & Payments
 Shane O'Sullivan
B2B Payments Market: 2026-2031
Our B2B Payments research suite provides a wide-ranging and rigorous analysis of this massive market; enabling stakeholders from B2B payment platform providers to regulators and banks, to understand future growth, key trends and the competitive environment.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Ardit Ballhysa
Robocalling & Branded Calling Market: 2026-2031
Our Robocalling & Branded Calling Market research suite provides insightful analysis of a market that is becoming increasingly dynamic and complex.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Peter Boyland
CPaaS Market: 2026-2031
Our CPaaS Market 2026-2031 research suite delivers insightful analysis of a market that will experience significant growth in the next five years. It provides an analysis of CPaaS vendors, key partnerships and client relationships, alongside intelligence on how to capitalise on changing market dynamics within the rapidly expanding CPaaS market.
VIEW -
 ReportOctober 2026Fintech & Payments
 Michael Greenwood
Accounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad Jahan
Crypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW


-
 WhitepaperNovember 2026Fintech & Payments
Lorien Carter
Is Agentic Commerce on the (Virtual) Cards?
Our complimentary whitepaper, Is Agentic Commerce on the (Virtual) Cards?, examines the state of the virtual cards market; explaining the role of key actors in the virtual cards landscape and recent developments within the virtual cards industry.
VIEW -
 WhitepaperNovember 2026Fintech & Payments
Shane O'Sullivan
The End of Wire Transfer – the Battle for B2B Payments
Our complimentary whitepaper, The End of Wire Transfer – the Battle for B2B Payments, examines the rapidly evolving state of the B2B payments market.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Ardit Ballhysa
Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond
Our complimentary whitepaper, Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond, explores the challenges and opportunities for fraud prevention.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Peter Boyland
Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS
Our complimentary whitepaper, Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS, explores the challenges and opportunities for operators and enterprises as CPaaS becomes more embedded in the consumer experience.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW


-
Telecoms & Connectivity
Private Networks in Service to Exceed 47,000 Globally by 2031, as Industry Specialisation & 5G Drive Expands
November 2026 -
Fintech & Payments
Virtual Cards Market Leaders Revealed by Juniper Research, as Revenue Forecast to Hit $148 Billion by 2031
November 2026 -
Fintech & Payments
B2B Payment Transactions to Exceed 612 Billion by 2031, as Fintechs Challenge Banks for Business Payment Relationships
November 2026 -
Fintech & Payments
27th NextGen Payments & RegTech Forum Returns to Limassol, Cyprus
November 2026 -
Telecoms & Connectivity
North American Consumer Losses from Fraudulent Robocalls to Fall by a Third by 2031; Driven by Robust Solutions and Branded Calling
November 2026 -
Telecoms & Connectivity
CPaaS Market Value to Exceed $50 Billion Globally by 2031, as Infobip, Twilio, and Sinch Identified as Market Leaders
November 2026