The Age of Composable Finance: Why AI-driven Orchestration Is Redefining Product Creation

The banking and fintech ecosystem is moving faster than ever, with competition intensifying, digital payments becoming increasingly popular, and new digital products launching every day. Alongside this, we have seen the rise of the Application Programming Interface (API), which means bank and fintech operations are more connected than ever.
As financial services increasingly embed into everyday digital journeys across eCommerce, mobility, and Software-as-a-Service (SaaS) ecosystems, every digital business now has the opportunity to offer fintech-powered products. However, the ability to do so is often limited by custom development cycles and developer bottlenecks, which slow down experimentation and scale.
Launching new products, particularly for less digitally enabled companies, can take months of coordination across different functions such as technology, compliance, operations, marketing, and others. This slows down the speed of iteration and threatens to leave slower-moving companies exposed to competition.
The technical situation around product development has been changing, but these changes have created issues of their own. For example, APIs have proliferated and are now a common and effective way to link different systems together. However, a lack of API standardisation and the resulting requirements to integrate APIs on a custom basis are a major challenge. The current situation has three major challenges:
- Slow product launches: API integration is a necessary step, but the time to integrate the API into other systems can slow down the velocity of product launches.
- Developer dependence: As APIs are not heavily standardised, they typically require customised developer work, which can make adjusting systems quickly difficult.
- Cost of integration debt: Due to outdated integrations, banks and fintechs are losing productivity; costing themselves money and increasing their time to market for new products.
In this context then, major changes are needed to ensure the success of product development within banking and fintech. The next major advance is composability, which can reshape the way new products are created and launched.
The Shift from APIs to Composability
Fundamentally, the last decade of fintech progress, which has seen enormous growth, was built on APIs. This has been a powerful approach, but is still highly fragmented and is slowing progress as fintech becomes increasingly competitive and fast moving.
With these challenges in mind, composability is set to be the new paradigm for banks and fintechs. We define composability as follows:
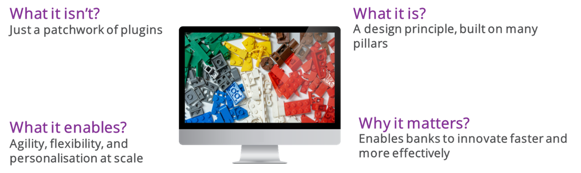
"The design of systems using independent, reusable building blocks, called primitives, which can be orchestrated dynamically into any journey."
Composability is not about more APIs - which will remain important - it is about abstraction; reducing building customer journeys into digestible steps. It is about governance; ensuring that banks and fintechs can have full visibility and ensure secure processes by design. Critically, it is about being able to seamlessly reuse components throughout operations; reducing investment and time to market.
Figure 1: What is Composability, Really?
Source: Juniper Research
Composability is fundamentally suitable for the evolving banking market. Banks and fintechs have been increasingly moving towards modular banking systems, where individual elements of their systems can be updated independently and linked via APIs, rather than undergoing full core system transformations.
Embedded finance also continues to rise as a trend; requiring banks and fintechs to integrate into different apps, systems, and user journeys. Alongside this, orchestration is becoming vital in banking, whether this is orchestrating payments acceptance, different banking systems, or different third-party capabilities.
In several ways, banking is undergoing a fundamental shift from a slow-moving, closed ecosystem defined by long-term loyalty to brands, to a new paradigm where banks have to move fast, create a more open ecosystem, and actively win customers with effective personalisation.
The Missing Link: Intelligence
However, even in a composable ecosystem, there is still heavy lifting needed from humans. In composable systems, humans must still manually stitch logic, dependencies, and compliance. This process, while faster than older models in the market, still takes considerable time and expertise; denying the optimum process for banks and fintechs looking to innovate.
Fundamentally, it is the emerging role of AI to close this loop. AI, when deployed with composable tools, can interpret intent, suggest workflows, infer parameters, and automate the connective tissue between APIs. This unlocks innovation by banks and fintechs; by using AI as an assistive tool to plan their systems, they can unlock their potential at a much faster rate of iteration.
This shift to AI-assisted development is not unusual in the wider context of software development. AI tools are becoming increasingly common for development; unlocking efficiency. However, what is different is that these tools typically lack the specific fintech and banking experience, without preset API linkages or logic that really works for banks and fintechs. Using a more specific tool will reap dividends in terms of a more efficient and tailored process.
The Rise of AI-led Product Composition Platforms
To summarise, we foresee the rise of AI-led product composition platforms for banks and fintechs enabling a new era of flexibility, faster iteration, and customer success. These platforms combine:
- AI orchestration: providing a comprehensive experience from prompt to deployable workflow.
- Composable blocks: prebuilt, compliant modules for fintech use cases; speeding up time to market.
- Unified governance: ensuring compliance and security across flows; making reporting and compliance far simpler.
Fundamentally, this represents an industry evolution towards greater customisation, faster time to market, and greater use of AI for orchestration. Demand from banks and fintechs will increase, as competition intensifies and as operating models such as embedded finance become increasingly relevant. As such, we expect far greater use of AI-led product composition platforms in the industry.
Example in Action – MobiFin Tapestry
One such platform in the market is MobiFin’s Tapestry, which is Fintech’s first AI-led product composer. Unveiled at Money20/20 USA, Tapestry empowers digital businesses to overcome developer bottlenecks and compose entire financial workflows through natural language prompts and composable building blocks.
By bringing together AI-powered workflow generation, prebuilt Fintech templates, and dynamic API orchestration, it showcases how financial products can move from concept to launch in days, not months. Click here to discover how Tapestry can help your organisation build faster, innovate smarter, and stay ahead of the competition.
Nick Maynard is VP of Fintech Market Research at Juniper Research, where he leads analysis on key trends shaping the future of finance. With deep expertise across digital payments and commerce, his recent work includes reports on Chargeback Management, Digital Commerce, and Payment Card Technologies; helping stakeholders stay ahead in a rapidly evolving market.
Latest research, whitepapers & press releases
-
 ReportNovember 2026Fintech & Payments
 Lorien Carter
Virtual Cards Market: 2026-2031
Our Virtual Cards research suite provides a comprehensive and in-depth analysis of the role of virtual cards in the digital payments landscape
VIEW -
 ReportNovember 2026Fintech & Payments
 Shane O'Sullivan
B2B Payments Market: 2026-2031
Our B2B Payments research suite provides a wide-ranging and rigorous analysis of this massive market; enabling stakeholders from B2B payment platform providers to regulators and banks, to understand future growth, key trends and the competitive environment.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Ardit Ballhysa
Robocalling & Branded Calling Market: 2026-2031
Our Robocalling & Branded Calling Market research suite provides insightful analysis of a market that is becoming increasingly dynamic and complex.
VIEW -
 ReportNovember 2026Telecoms & Connectivity
 Peter Boyland
CPaaS Market: 2026-2031
Our CPaaS Market 2026-2031 research suite delivers insightful analysis of a market that will experience significant growth in the next five years. It provides an analysis of CPaaS vendors, key partnerships and client relationships, alongside intelligence on how to capitalise on changing market dynamics within the rapidly expanding CPaaS market.
VIEW -
 ReportOctober 2026Fintech & Payments
 Michael Greenwood
Accounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad Jahan
Crypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW


-
 WhitepaperNovember 2026Fintech & Payments
Lorien Carter
Is Agentic Commerce on the (Virtual) Cards?
Our complimentary whitepaper, Is Agentic Commerce on the (Virtual) Cards?, examines the state of the virtual cards market; explaining the role of key actors in the virtual cards landscape and recent developments within the virtual cards industry.
VIEW -
 WhitepaperNovember 2026Fintech & Payments
Shane O'Sullivan
The End of Wire Transfer – the Battle for B2B Payments
Our complimentary whitepaper, The End of Wire Transfer – the Battle for B2B Payments, examines the rapidly evolving state of the B2B payments market.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Ardit Ballhysa
Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond
Our complimentary whitepaper, Deepfakes in Robocalling Fraud – the Need for Advanced Solutions and Frameworks in 2027 and Beyond, explores the challenges and opportunities for fraud prevention.
VIEW -
 WhitepaperNovember 2026Telecoms & Connectivity
Peter Boyland
Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS
Our complimentary whitepaper, Rich Messaging, Real Growth: the Rise of RCS and OTT in CPaaS, explores the challenges and opportunities for operators and enterprises as CPaaS becomes more embedded in the consumer experience.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW


-
Telecoms & Connectivity
Private Networks in Service to Exceed 47,000 Globally by 2031, as Industry Specialisation & 5G Drive Expands
November 2026 -
Fintech & Payments
Virtual Cards Market Leaders Revealed by Juniper Research, as Revenue Forecast to Hit $148 Billion by 2031
November 2026 -
Fintech & Payments
B2B Payment Transactions to Exceed 612 Billion by 2031, as Fintechs Challenge Banks for Business Payment Relationships
November 2026 -
Fintech & Payments
27th NextGen Payments & RegTech Forum Returns to Limassol, Cyprus
November 2026 -
Telecoms & Connectivity
North American Consumer Losses from Fraudulent Robocalls to Fall by a Third by 2031; Driven by Robust Solutions and Branded Calling
November 2026 -
Telecoms & Connectivity
CPaaS Market Value to Exceed $50 Billion Globally by 2031, as Infobip, Twilio, and Sinch Identified as Market Leaders
November 2026