The Fight to Power Agent-Initiated Payments
Source: Visa
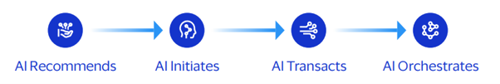
The first stage of integration of AI into the buying process is already well underway. AI can research and compare products for customers, and make tailored recommendations based on prompts. This is enabled by interfaces such as the Model Context Protocol; a framework that enables LLMs and AI agents to interact directly with a business’s systems and query product data in real time. In response to this, retailers have started to optimise their websites for AI agents by structuring their data for AI discovery.
The next stage of commerce involves AI initiating payments on a user’s behalf, with the user confirming and authorising each transaction. An example of this is OpenAI’s Operator, which is available to Pro users in the US, and can interact with websites and independently execute tasks such as ordering groceries, or creating a travel itinerary. However, AI can only take the person up to the checkout process, and the user must enter in its payment credentials and authorise the order.
The next logical step in this process is for AI agents to operate with less human intervention, and finalise the purchases. However, this is not possible with the current payments’ infrastructure of today. Either AI platforms must be turned into digital wallets, or dedicated new systems designed to operate within AI ecosystems must be implemented by payments providers. With agentic commerce spend forecast to generate $1.5 trillion globally by 2030 - nearly matching the $1.9 trillion of payments processed by Stripe in 2025 - the companies that process AI payment workflows will become the most important players in the next generation of digital commerce.
Recognising this opportunity, the world’s largest payment networks are already positioning themselves to become the infrastructure layer for agentic commerce. Last week at the Visa Payments Forum in San Francisco, Visa announced a partnership with OpenAI to enable agent-initiated payments inside chatbot ecosystems. This comes on the heels of Mastercard announcing an expansion of a similar initiative; named Mastercard Agent Pay, two weeks prior.
The Technology Behind Agent Payments
Tokenisation lies at the heart of these initiatives. Visa uses scoped tokenised credentials, which ensure that a token issued for a clothes shopping agent cannot be used outside of that purpose. Under this model, Visa will be responsible for payment tokenisation; ensuring that agents making purchases are identified and authorised, and implementing fraud monitoring. The buyer will remain in control through permission layers, spending limits, and required approval thresholds.
Mastercard has a similar approach, where every agent is credentialled, and can be recognised and transact across ecosystems. Organisations can set authorisation rules and programmatically enforce spending limits on their AI agents. Mastercard’s Agent Pay Programme also acts as a checkout solution; supporting merchants in agentic commerce through its Mastercard Agent Pay Acceptance Framework.
Which Industries Will Be Disrupted by AI?
The consumer use case is the largest unknown. While users may be interested in using AI for researching products, trusting AI to carry out the final purchase is a large behavioural jump. It also cuts out hobbyist shoppers, who enjoy the entire process of browsing, reading reviews, and purchasing. While there are specific use cases where AI agents can deliver clear value - waiting in online queues to purchase tickets, or submitting bids on eBay just before the listing closes - everyday shopping experiences involve enjoyment that customers may be unwilling to delegate to AI.
The cost of using these agents is another prohibitive factor. While users of free AI plans have skyrocketed since its introduction, OpenAI has recently shared data that out of the 800 million users of their AI tools, only 35 million are paid; a 4% conversion rate. Currently, people do not seem willing to pay for more advanced AI capabilities, although that may change as they improve. AI agents will require a lot more power per search than current queries do; suggesting that subscription fees may need to increase to accommodate that. This is already beginning to happen. Anthropic’s Claude recently changed its pricing model to charge enterprise customers based on their level of AI usage, rather than a flat subscription fee. With demand already low despite subscriptions being relatively affordable, it is uncertain whether consumers would still buy these plans if the price increased.
Uncertainties around consumer demand may be why Mastercard’s expansion is targeting a slightly different segment: machine-to-machine payments. Agent Pay for Machines (AP4M), introduced last week, will power automated microtransactions that happen in the background of digital commerce. For example, a logistics AI agent could pay for loading-bay access and settle warehouse handling fees automatically throughout the lifespan of a shipment. Mastercard will settle payments across multiple rails, including cards, bank accounts, and stablecoins.
“Agent Pay for Machines will create the conditions for a superbloom of AI business models,” said Jorn Lambert, Mastercard’s Chief Product Officer.
There has been high industry interest in this development. Partners for AP4M include payment service providers such as Adyen and Stripe, stablecoin settlement networks including BVNK and Ripple, and SaaS providers such as Cloudflare.
AI Payments Are Going Live
The vision of agentic commerce is well underway to being realised; moving from concept to reality. By the end of March this year, OpenAI had closed its latest funding round with $122 billion in committed capital, backed by companies such as Amazon, NVIDIA, and Microsoft. With this investment, OpenAI has announced its intention to build an AI superapp that brings together ChatGPT, Codex, browsing, and broader agentic capabilities into an agent-first experience. The ability to make trusted, secure payments within this system will be key for encouraging consumer adoption.
Both Visa and Mastercard have been laying the foundations for AI-native commerce. Proof of concepts have already been carried out. In Europe, the first live end-to-end payment executed by an AI agent was conducted in March 2026 by Santander and Mastercard. The only question that remains is who will provide the infrastructure once independent AI-initiated payments begin to scale - if they ever do.
Related Research
-
 ReportMarch 2026Fintech & Payments
 Michael Greenwood
B2B Payment Cards Market, 2026-2030
Our B2B card payments research suite provides detailed analysis of this rapidly changing market; allowing B2B card providers to gain an understanding of key payment trends and challenges, potential growth opportunities, and the competitive environment.
VIEW -
 ReportFebruary 2026Fintech & Payments
 Jawad Jahan
Mobile Money in Emerging Markets, 2026-2030
Our Mobile Money in Emerging Markets research report provides detailed evaluation and analysis of the ways in which the mobile financial services space is evolving and developing.
VIEW
Latest research, whitepapers & press releases
-
 ReportNovember 2026Telecoms & Connectivity
 Peter Boyland
CPaaS Market: 2026-2031
Our CPaaS Market 2026-2031 research suite delivers insightful analysis of a market that will experience significant growth in the next five years. It provides an analysis of CPaaS vendors, key partnerships and client relationships, alongside intelligence on how to capitalise on changing market dynamics within the rapidly expanding CPaaS market.
VIEW -
 ReportOctober 2026Fintech & Payments
 Michael Greenwood
Accounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad Jahan
Crypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW -
 ReportOctober 2026Telecoms & Connectivity
 Alex Webb
Retail Roaming Market: 2026-2031
Our Retail Roaming research suite for mobile network operators (MNOs) and mobile virtual network operators (MVNOs) provides detailed analysis and strategic recommendations for the next era of retail roaming.
VIEW -
 ReportSeptember 2026Fintech & Payments
 Dr Manju Chhillar
Embedded Finance Market: 2026-2031
Embedded finance is one of the fastest-growing markets in financial services, and is about to accelerate even further. Our Embedded Finance Market research provides detailed analysis of the key drivers behind this growth, and what these mean for stakeholders in this market.
VIEW -
 ReportSeptember 2026Identity & Security
 Thomas Wilson
Application Security Market: 2026-2031
Our Application Security research suite provides detailed analysis of this emerging market; allowing application security providers to gain an understanding of key security trends and challenges, potential growth opportunities, and the competitive environment.
VIEW


-
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW -
 WhitepaperOctober 2026Telecoms & Connectivity
Alex Webb
Reimagining the Future of Retail Roaming – How Mobile Network Operators Must Adapt
Our complimentary whitepaper, Reimagining the Future of Retail Roaming – How Mobile Network Operators Must Adapt, explores the emerging opportunities for MNOs within retail roaming.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
Dr Manju Chhillar
Emerging Markets: The Next Opportunity for Embedded Finance
This free whitepaper examines how a combination of multiple factors is driving North America towards saturation for embedded finance.
VIEW -
 WhitepaperSeptember 2026Emerging Technology
Thomas Wilson
Vibe Coding: The Fastest-growing Threat to Application Security Today
Our complimentary whitepaper, Vibe Coding: The Fastest-growing Threat to Application Security Today, examines the state of the application security market; considering its impact on different verticals, and how it is being employed in these verticals to best combat malicious attackers and keep sensitive data safe.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
 Shane O'Sullivan
The Fraud Frontier: Securing Banking in an AI-driven Era
Our complimentary whitepaper, The Fraud Frontier: Securing Banking in an AI-driven Era, examines the rapidly evolving state of the banking fraud prevention market.
VIEW


-
Fintech & Payments
26th NextGen Payments & RegTech Forum Arrives in Austin, Texas
October 2026 -
Fintech & Payments
Financial Institutions to Spend Over $66.2 Billion Globally on Fraud Prevention by 2031, Driven by Growing Demand for Cross-industry Fraud Intelligence
October 2026 -
Fintech & Payments
Omnichannel Payment Platforms to See a Dramatic 172% Growth in the Value of Transactions Processed Globally by 2031, as Merchants Capitalise on Payment Data
October 2026 -
Fintech & Payments
Accounts Payable Automation to Save Global Businesses 6.2 Billion Hours by 2031, Accelerated by Business System Integration
October 2026 -
Fintech & Payments
The 25th NextGen Payments & RegTech Forum Arrives in Athens, Greece
October 2026 -
Fintech & Payments
Crypto Gaming: Wagers to Reach $1.3 Trillion by 2035, as Crypto Rails Widen Global Access Despite Regulatory Challenges
October 2026