What Happens When Data Bundles Eclipse Consumer Demand?
At the start of the 5G era, the mobile ecosystem was inundated with hype about the future potential of mobile data growth. Propelled by use cases such as 8K video, augmented reality, and cloud gaming, the era of 5G was expected to be defined by continued leaps in mobile data demand and usage by consumers.
Demand for these use cases has never really materialised as significant drivers of mobile data growth, with increases being driven by use cases such as video streaming and short form video content. Enterprises delivering these services over mobile networks are also keen to minimise mobile data consumption, as this enables users to use their service for longer.
This means that new use cases are not driving demand, while existing use cases are working to minimise mobile data use. In contrast, mobile data allowances have continued to grow, and price per GB has fallen, particularly in markets such as the UK. This has led to the growth in data bundles eclipsing growth in consumer demand.
The UK’s Data Bundles Grow to Eclipse Average Mobile Data Usage
The cost per GB of mobile data in the UK has declined considerably in the past decade. In 2015, Ofcom reported that the price per GB of mobile data in the UK was £6.68. In 2026, consumers can now buy 5GB for less than £6.50 from Lebara Mobile, Smarty Mobile, and more. Moreover, the data bundles offered for under £10 per month often exceed 40 GB, and the cheapest unlimited plans start at less than £15 per month.
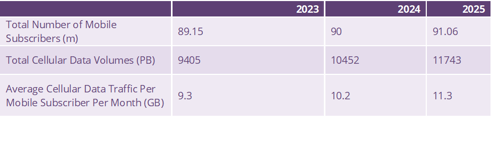
In contrast, in its telecommunications market data update, Ofcom reported total cellular data volume in the UK for 2025 as 11743 PB. Juniper Research notes that this traffic includes other end users such as fixed wireless access (FWA) connections. As FWA typically carries far higher data volume than individual mobile subscriptions, their inclusion in the total likely inflates the per-subscription average shown below; indicating that average data usage per mobile phone subscription is likely lower than 11.3 GB.
Table 1: Ofcom Quarterly Telecommunications Market Data Update July 2026
Source: Ofcom
Note: Average Cellular Data Traffic per Mobile Subscriber per Month was calculated by dividing the total cellular data volume by the year prior and year current average of mobile subscribers and 12 - other methodologies may vary in result.
The 11.3 GB per month figure is a fraction of the data bundles now being offered by many mobile service providers, with continued decline in cost per GB exacerbating this disparity. In a sense, the supply of mobile data in bundles is outstripping actual usage, suggesting data consumption is increasingly capped by consumer behaviour rather than by price or allowance size.
Whilst a large number of consumers still require increased data bundles, and most consumers will pay for some headroom between data bundles and actual usage; Juniper Research argues that a growing number of consumers perceive these data bundles as offering diminishing returns on investment.
According to Ofcom, the average monthly retail revenue per mobile subscriber in 2025 is £15.98 for a postpaid mobile subscriber (75% of total UK mobile subscribers). Under many Mobile Virtual Network Operators (MVNOs) and sub brands, this monthly cost can provide access to unlimited mobile data, whilst their consumers paying around two thirds of this monthly cost can access more than 40GB per month.
Without the emergence of new data-intensive mobile use cases, the UK mobile market is increasingly trending towards favouring those who can compete beyond data bundles. Consumers still value mobile data highly, but the apparent diminishing return on investment as GB bundles grow means the market must rethink how to differentiate.
What Could the Future of UK Mobile Subscriptions Look Like?
The principal question for UK MNOs, MVNOs, and other mobile players will be how they can compete beyond expanded data bundles. Data bundles will remain at the centre of the value proposition, but the value-added for consumers is declining as these data bundles grow.
Juniper Research expects that traditional offers of bundling and mobile roaming will likely grow in importance over the next five years. Bundles such as those including music and video streaming services enable consumers to reduce costs by consolidating their memberships into a single subscription. Mobile roaming services remain costly for consumers, suppressing demand; meaning cheaper or bundled roaming access stands to unlock demand that lower domestic pricing increasingly cannot. This is particularly relevant since the UK left the European Union (EU), meaning consumers there are no longer covered by EU roaming legislation when travelling within the bloc.
However, the most successful MNOs, MVNOs, and sub brands will go beyond these more traditional value propositions. Juniper Research expects the following trends to become increasingly common in the UK mobile market:
- Cross-business Value – A growing number of enterprises such as fintechs are becoming involved in mobile markets, enabled by telecommunications as a service providers such as Gigs and 1global. Juniper Research expects these enterprises will increasingly leverage their wider businesses over the next five years to add value to their mobile offers; thus creating a strong value proposition for consumers searching for a mobile subscription that goes beyond large data bundles.
- AI Services – Juniper Research expects that MNOs will introduce a number of AI-based value-added services to mobile subscriptions, such as AI assistants, that can leverage mobile channels to perform tasks such as restaurant and garage bookings. Freemium access via mobile subscriptions would provide MNOs with a strong value offer to consumers beyond basic data bundles, especially as increasingly these tasks will involve consumers communicating with AI on the enterprise side. Juniper Research expects that competition will be significant in this market, so MNO capacity to leverage their existing customer relationships and infrastructure will be critical.
- Quality-based Pricing – MNOs in particular are increasingly positioning their connectivity as a premium offer. For example, EE offers a number of unlimited data allowances with varying speed gaps which range from 10Mbps to uncapped. Juniper Research notes that this shows that data can still be the value proposition even if data bundles are not. MNOs could also explore competing on customer experience, offering premium access to services such as customer support.
In conclusion, Juniper Research argues that the future of UK mobile subscriptions will be oriented around how providers can deliver value beyond larger data bundles, including increased quality, cross business value offer, streaming bundles, and AI services.
Related Research
-
 ReportJune 2026Conversational AI
 Peter Boyland
Conversational AI Market, 2026-2030
Our Conversational AI Market 2026-2030 research suite provides insightful analysis of a market that will experience significant growth in the next five years.
VIEW -
 ReportJune 2026Telecoms & Connectivity
 Alex Webb
Direct to Cell Market, 2026-2031
Our newest Direct-to-Cell research provides market stakeholders, such as mobile network operators and satellite network operators, with key analysis of the future of this rapidly emerging market.
VIEW -
 ReportMay 2026Telecoms & Connectivity
Alex Webb
6G Market, 2026-2035
Our 6G Market research suite provides detailed analysis and strategic recommendations for mobile network operators developing their 6G roadmaps in the build up to its standardisation and launch.
VIEW
Latest research, whitepapers & press releases
-
 ReportNovember 2026Telecoms & Connectivity
 Peter Boyland
CPaaS Market: 2026-2031
Our CPaaS Market 2026-2031 research suite delivers insightful analysis of a market that will experience significant growth in the next five years. It provides an analysis of CPaaS vendors, key partnerships and client relationships, alongside intelligence on how to capitalise on changing market dynamics within the rapidly expanding CPaaS market.
VIEW -
 ReportOctober 2026Fintech & Payments
 Michael Greenwood
Accounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad Jahan
Crypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW -
 ReportOctober 2026Telecoms & Connectivity
 Alex Webb
Retail Roaming Market: 2026-2031
Our Retail Roaming research suite for mobile network operators (MNOs) and mobile virtual network operators (MVNOs) provides detailed analysis and strategic recommendations for the next era of retail roaming.
VIEW -
 ReportSeptember 2026Fintech & Payments
 Dr Manju Chhillar
Embedded Finance Market: 2026-2031
Embedded finance is one of the fastest-growing markets in financial services, and is about to accelerate even further. Our Embedded Finance Market research provides detailed analysis of the key drivers behind this growth, and what these mean for stakeholders in this market.
VIEW -
 ReportSeptember 2026Identity & Security
 Thomas Wilson
Application Security Market: 2026-2031
Our Application Security research suite provides detailed analysis of this emerging market; allowing application security providers to gain an understanding of key security trends and challenges, potential growth opportunities, and the competitive environment.
VIEW


-
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW -
 WhitepaperOctober 2026Telecoms & Connectivity
Alex Webb
Reimagining the Future of Retail Roaming – How Mobile Network Operators Must Adapt
Our complimentary whitepaper, Reimagining the Future of Retail Roaming – How Mobile Network Operators Must Adapt, explores the emerging opportunities for MNOs within retail roaming.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
Dr Manju Chhillar
Emerging Markets: The Next Opportunity for Embedded Finance
This free whitepaper examines how a combination of multiple factors is driving North America towards saturation for embedded finance.
VIEW -
 WhitepaperSeptember 2026Emerging Technology
Thomas Wilson
Vibe Coding: The Fastest-growing Threat to Application Security Today
Our complimentary whitepaper, Vibe Coding: The Fastest-growing Threat to Application Security Today, examines the state of the application security market; considering its impact on different verticals, and how it is being employed in these verticals to best combat malicious attackers and keep sensitive data safe.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
 Shane O'Sullivan
The Fraud Frontier: Securing Banking in an AI-driven Era
Our complimentary whitepaper, The Fraud Frontier: Securing Banking in an AI-driven Era, examines the rapidly evolving state of the banking fraud prevention market.
VIEW


-
Fintech & Payments
26th NextGen Payments & RegTech Forum Arrives in Austin, Texas
October 2026 -
Fintech & Payments
Financial Institutions to Spend Over $66.2 Billion Globally on Fraud Prevention by 2031, Driven by Growing Demand for Cross-industry Fraud Intelligence
October 2026 -
Fintech & Payments
Omnichannel Payment Platforms to See a Dramatic 172% Growth in the Value of Transactions Processed Globally by 2031, as Merchants Capitalise on Payment Data
October 2026 -
Fintech & Payments
Accounts Payable Automation to Save Global Businesses 6.2 Billion Hours by 2031, Accelerated by Business System Integration
October 2026 -
Fintech & Payments
The 25th NextGen Payments & RegTech Forum Arrives in Athens, Greece
October 2026 -
Fintech & Payments
Crypto Gaming: Wagers to Reach $1.3 Trillion by 2035, as Crypto Rails Widen Global Access Despite Regulatory Challenges
October 2026